Retail accounting applies accounting to a business that sells to end consumers through many small transactions: point-of-sale (POS) invoices in branches, online store and marketplace orders, collections in cash, cards and cash on delivery, and fast-moving inventory. Keeping it under control rests on two things: a daily close that matches sales to cash and settlements, and correct application of two Standards, IFRS 15 for revenue (discounts, returns, loyalty points, marketplaces) and IAS 2 for inventory (cost, net realisable value, shrinkage).
What makes retail accounting different?
Transactions are many and each one is small, so an error repeated thousands of times becomes a large loss; payment methods, items, promotions and returns multiply, and shrinkage and expiry appear.
When is revenue recognised? An entity shall recognise revenue when it satisfies a performance obligation by transferring a promised good to a customer, and the good is transferred when the customer obtains control of it (IFRS 15.31). To determine that point, for example for an online order under its delivery terms, the entity shall consider indicators that include, but are not limited to, its present right to payment, the customer's legal title, the transfer of physical possession, the customer having the significant risks and rewards of ownership, and the customer's acceptance of the asset (IFRS 15.38). A right of return does not prevent the transfer of control; it reduces the amount of revenue by the goods expected to be returned (IFRS 15.B20–B21). For the full framework, see IFRS 15 Revenue from Contracts with Customers.
The POS cycle and the daily close
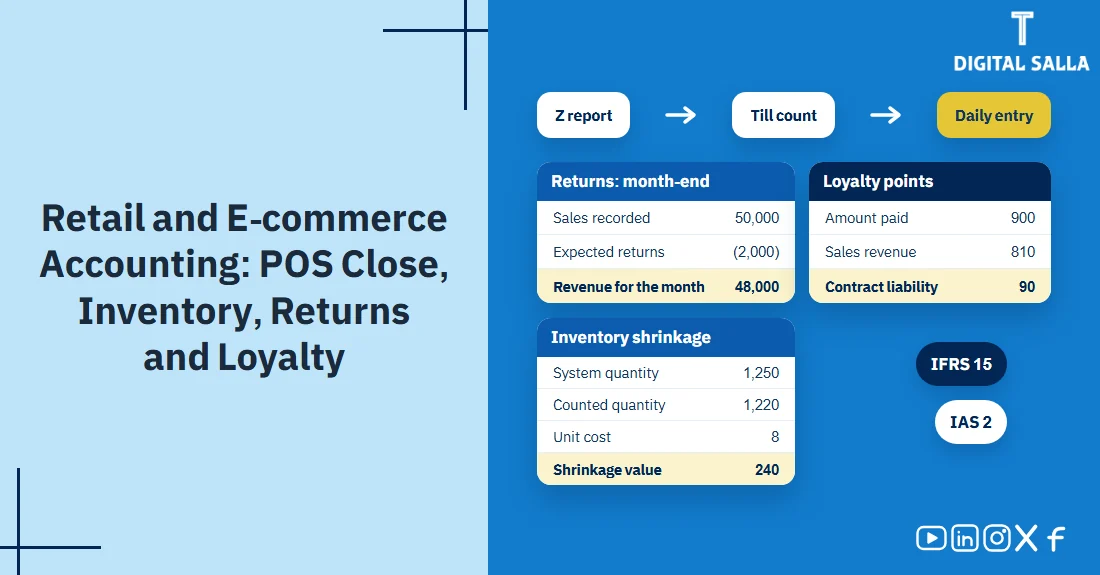
Fix a daily cycle that never changes: sales invoices → Z report → till count → card sales to a clearing account → daily entry → exception review and close.
Daily sales entry — illustrative
| Account | Debit | Credit |
|---|---|---|
| Cash on hand (per count) | XXX | |
| Card settlements (clearing) | XXX | |
| Sales revenue (by branch and channel) | XXX | |
| Output tax (if any) | XXX |
Output tax collected on behalf of the tax authority goes to its own account, not to revenue, because the transaction price is the consideration the entity expects to be entitled to, excluding amounts collected on behalf of third parties, such as some sales taxes (IFRS 15.47). See VAT journal entries.
Cash, cards and payment gateways
A frequent source of differences is collection rather than the sale itself: what actually arrives after fees, declined transactions and chargebacks. So record card sales daily in a clearing account rather than straight to the bank, open one clearing account per channel and provider, and review their ageing weekly. When the settlement arrives:
| Account | Debit | Credit |
|---|---|---|
| Bank | Net settlement | |
| Merchant fees (MDR) expense | Fees | |
| Card clearing account | Gross card sales |
Till controls in branches
- A fixed opening float for each cashier, with a signed handover note.
- Blind, dual counts: the cashier counts without seeing the system balance, then a supervisor reviews and both sign.
- Cash drops whenever till cash exceeds an approved limit, and no payments out of the till without a voucher.
- A separate cash over/short account, kept out of general expenses, so patterns show by branch, cashier and shift.
To reconcile the bank account itself: bank reconciliation step by step.
The online channel: order ID, cash on delivery and marketplaces
"Paid" in the store platform does not mean the money has reached the bank. Make the order ID the common reference for every entry and settlement, and use it to match four sources: the store platform (orders, discounts, cancellations, partial returns), the payment gateway (settlements, fees, chargebacks), the carrier (delivery, its cost and COD collections) and the bank (net receipts and their dates).
Cash on delivery (COD)
The carrier collects from the customer and remits the net amount after its fees. Record amounts collected on delivery in a COD clearing account until the remittance arrives, and do not treat "out for delivery" as collected:
| Account | Debit | Credit |
|---|---|---|
| Bank | Net carrier remittance | |
| Collection and shipping fees | Fees | |
| COD clearing account | Gross collections |
A growing balance usually signals collections not yet remitted or disputes, so review its ageing weekly.
Selling through marketplaces
When another party is involved in providing goods to a customer, the entity shall determine, for each specified good or service, whether it is a principal, promising to provide it itself, or an agent, promising to arrange for the other party to provide it (IFRS 15.B34). It is a principal if it controls the good before it is transferred to the customer, although obtaining legal title only momentarily before title passes to the customer does not necessarily mean control (IFRS 15.B35); indicators of control include, but are not limited to, primary responsibility for fulfilment, inventory risk and discretion in establishing the price (IFRS 15.B37).
- You sell your own inventory through a platform as principal: your revenue is the gross amount of consideration you expect to be entitled to for the goods (IFRS 15.B35B), and the platform's commissions and fees go to a separate account.
- You run a platform for other sellers' goods as an agent: your revenue is the fee or commission you expect to be entitled to (IFRS 15.B36).
Open a clearing account per platform, and record who funds each discount (you or the platform) from the settlement statement. Keep shipping charged to customers separate from the delivery costs you bear, because channel margin needs both figures.
Discounts, coupons and loyalty points
The amount of consideration can vary because of discounts, rebates, refunds, credits, price concessions, incentives, performance bonuses, penalties or other similar items (IFRS 15.51). Give every discount a code and a reason in the POS, and separate the types:
- Price discounts and coupons used at the purchase: they reduce the selling price itself.
- Bundles: if the sum of the stand-alone selling prices exceeds the bundle price, the discount shall be allocated proportionately to all performance obligations, unless the entity has observable evidence, meeting all three criteria in paragraph 82, that the entire discount relates to only some of them (IFRS 15.81–82). This matters for item margins and for the value of a partial return.
- Loyalty points and vouchers for future purchases: not a "contingent liability". Such an option gives rise to a performance obligation only if it provides the customer with a material right it would not receive without this purchase (such as a discount incremental to the range of discounts typically given for those goods to that class of customer in that geographical area or market); the customer then in effect pays in advance for future goods, and revenue is recognised when those goods are transferred or when the option expires (IFRS 15.B40). If the option is priced at the stand-alone selling price, there is no material right; it is a marketing offer that shall be accounted for only when the customer exercises it (IFRS 15.B41).
Illustrative example (assumed figures): a customer pays 900 for goods with a stand-alone selling price of 900 and earns points worth a 125 discount on future purchases. Assumptions: the points are a material right, their stand-alone selling price is not directly observable, the customer could get no discount without them, the entity expects 80% to be redeemed, and amounts exclude tax. The estimate shall reflect the discount adjusted for any discount available without the points (nil) and for the likelihood of exercise (IFRS 15.B42): 125 × 80% = 100. The 900 paid is then allocated on relative stand-alone selling prices (900 + 100 = 1,000):
| Account | Debit | Credit |
|---|---|---|
| Cash | 900 | |
| Sales revenue (900 × 900 ÷ 1,000) | 810 | |
| Contract liability — loyalty points (900 × 100 ÷ 1,000) | 90 |
The 90 shall be presented as a contract liability because the customer paid before the future goods are transferred (IFRS 15.106). If the entity uses the ratio of points redeemed to points expected to be redeemed, and half of the points expected to be redeemed have been redeemed, it moves 45 (90 × 50%) from the contract liability to revenue.
Returns and exchanges
No return without a document and an authorised approver; separate resaleable returns from damaged ones and match returns to inventory movements. For sales with a right of return, an entity shall recognise all of the following (IFRS 15.B21):
- Revenue at the amount of consideration it expects to be entitled to, that is, excluding goods expected to be returned.
- A refund liability for what it expects to refund.
- An asset for its right to recover the goods from customers, with a corresponding adjustment to cost of sales.
The asset shall initially be measured at the former carrying amount of the goods less any expected costs to recover them, including potential decreases in their value; its measurement shall be updated at the end of each reporting period, and it shall be presented separately from the refund liability (IFRS 15.B25). The refund liability and the estimate of the consideration the entity expects to be entitled to shall also be updated at the end of each reporting period, with corresponding adjustments recognised as revenue or reductions of revenue (IFRS 15.B23–B24). Exchanging one product for another of the same type, quality, condition and price (one size for another) is not a return (IFRS 15.B26), and a defective product returned for a working one shall be evaluated under the warranty guidance (IFRS 15.B27).
Illustrative example (assumed figures): sales recorded for the month are 50,000 at a cost of 30,000, with returns allowed within 30 days. From experience, the entity expects goods from those sales priced at 2,000, costing 1,200, to be returned after month-end, all resaleable with no recovery costs; amounts exclude tax. Month-end entry:
| Account | Debit | Credit |
|---|---|---|
| Sales revenue | 2,000 | |
| Refund liability | 2,000 | |
| Right to recover returned goods | 1,200 | |
| Cost of sales | 1,200 |
Revenue for the month becomes 48,000 and cost of sales 28,800. On the actual return: debit the refund liability and credit cash or the clearing account; debit inventory and credit the right-to-recover asset.
Inventory: cost, stocktakes and shrinkage
Inventories shall be measured at the lower of cost and net realisable value (IAS 2.9). The costs of purchase comprise the purchase price, import duties and other non-recoverable taxes, transport, handling and other costs directly attributable to the acquisition; trade discounts, rebates and similar items are deducted (IAS 2.11), so keep a register of supplier rebates matched to their invoices.
- Cost formulas: items not ordinarily interchangeable, and goods or services produced and segregated for specific projects, shall be costed by specific identification of their individual costs (IAS 2.23); the cost of other inventories shall be assigned using first-in, first-out (FIFO) or weighted average cost, and the same formula shall be used for all inventories of a similar nature and use (IAS 2.25). See inventory valuation methods.
- The retail method: may be used for convenience if the results approximate cost (IAS 2.21). It is often used in retail for large numbers of rapidly changing items with similar margins for which other costing methods are impracticable: the sales value of inventory is reduced by the appropriate percentage gross margin, taking marked-down stock into account, and an average percentage for each retail department is often used (IAS 2.22).
- Damaged and expired stock: cost may not be recoverable if inventories are damaged, have become wholly or partially obsolete or their selling prices have declined, or if the estimated costs of completion or the estimated costs to be incurred to make the sale have increased (IAS 2.28); where net realisable value falls below cost, inventories shall be written down to it (IAS 2.9), net realisable value being the estimated selling price in the ordinary course of business less the estimated costs of completion and the estimated costs necessary to make the sale (IAS 2.6).
In operations: a perpetual system with frequent cycle counts of high-movement items, a documented route for damaged goods, and branch transfers with dispatch and receipt notes.
Stocktake step by step
- Set the scope: a full count of a branch or warehouse, or a cycle count of selected items.
- Freeze movements during the count, and document what cannot be frozen.
- Prepare count sheets by item and location, with no unauthorised manual edits.
- Count independently, then review, and recount sensitive items.
- Compare with the system, extract the differences and analyse their causes.
- Approve the differences within authority limits.
- Post the adjusting entries and keep the count file with its minutes and causes.
Measuring and recording shrinkage
- Shrinkage value = (system quantity − counted quantity) × unit cost under the entity's cost formula.
- Shrinkage rate = shrinkage value ÷ net sales (or ÷ cost of sales); choose one denominator and keep it.
The amount of any write-down of inventories to net realisable value and all losses of inventories shall be recognised as an expense in the period the write-down or loss occurs (IAS 2.34). Illustrative example (assumed figures): the system shows 1,250 units, 1,220 are counted and the weighted average unit cost is 8, so shrinkage is 30 × 8 = 240:
| Account | Debit | Credit |
|---|---|---|
| Inventory shrinkage expense | 240 | |
| Inventory | 240 |
Analyse shrinkage before posting by cause (theft, damage, expiry, pricing or transfer errors), branch and category. For more: inventory adjustments.
Chart of accounts and cost centres
| Account group | Examples | Analysis dimension |
|---|---|---|
| Revenue | Branch, online store and marketplace sales | Channel and branch |
| Discounts, returns and loyalty | Discounts, refund liability, right-to-recover asset, contract liability for points | Campaign and return reason |
| Collection | Cash, bank, a clearing account per channel, provider and platform, COD | Payment method and provider |
| Inventory and cost of sales | Branch and warehouse stock, shrinkage, damaged goods | Location and category |
| Channel expenses | Merchant, gateway and platform fees, shipping, cash over/short | Channel |
To build the chart itself: chart of accounts design. If the company runs several activities (retail, distribution, services): industry-specific accounting.
Management reports and KPIs
- Gross margin by category = (net sales − cost of sales) ÷ net sales.
- Inventory turnover = cost of sales ÷ average inventory.
- Cost of sales under a periodic system = opening inventory + purchases − closing inventory.
- Shrinkage, expiry and returns reports by cause, branch, cashier and channel.
- Settlement ageing for each gateway, platform and carrier.
- For the online store: fees as a percentage of sales, shipping cost per order, and a net revenue bridge from gross sales to net cash.
For broader operating indicators: retail performance indicators.
Daily controls
Daily close checklist: the Z report matched to the day's invoices, the counted cash and the bank settlements; a documented till count; a daily entry split by payment method and channel; a review of negative stock items; and clearing accounts reconciled, or at least a weekly ageing.
To write these controls up as approved procedures: Financial Policies and Procedures Manual with Authority Matrix and Internal Controls, a Word manual with procedures for eleven cycles, including sales and collection, cash and banks, and inventory, and an Excel file with the authority and controls matrices, segregation-of-duties conflicts and a risk register. Its content is a proposal to adapt and then approve; it is written for companies and is not retail-specific.
Sources
- IFRS Foundation: IFRS 15 Revenue from Contracts with Customers. References in brackets are to paragraphs of the Standards.
- IFRS Foundation: IAS 2 Inventories.