Digital Product
Zakat & Tax499349
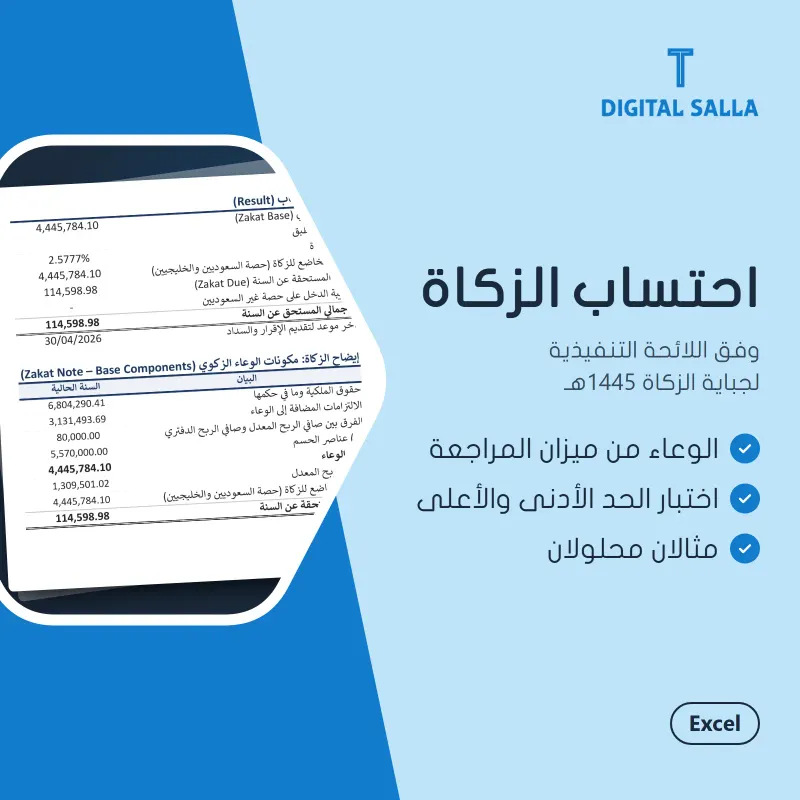
Zakat Calculation Model
Compute the zakat base from the trial balance under the new implementing regulations, with the minimum-base test, mixed-ownership companies, the provision entry, and two solved examples.
Instant delivery after payment · Secure payment: cards, Apple Pay and Google Pay · A year of free updates
Professional tools, services, and content — everything disciplined accounting work needs.
29 results
Compute the zakat base from the trial balance under the new implementing regulations, with the minimum-base test, mixed-ownership companies, the provision entry, and two solved examples.
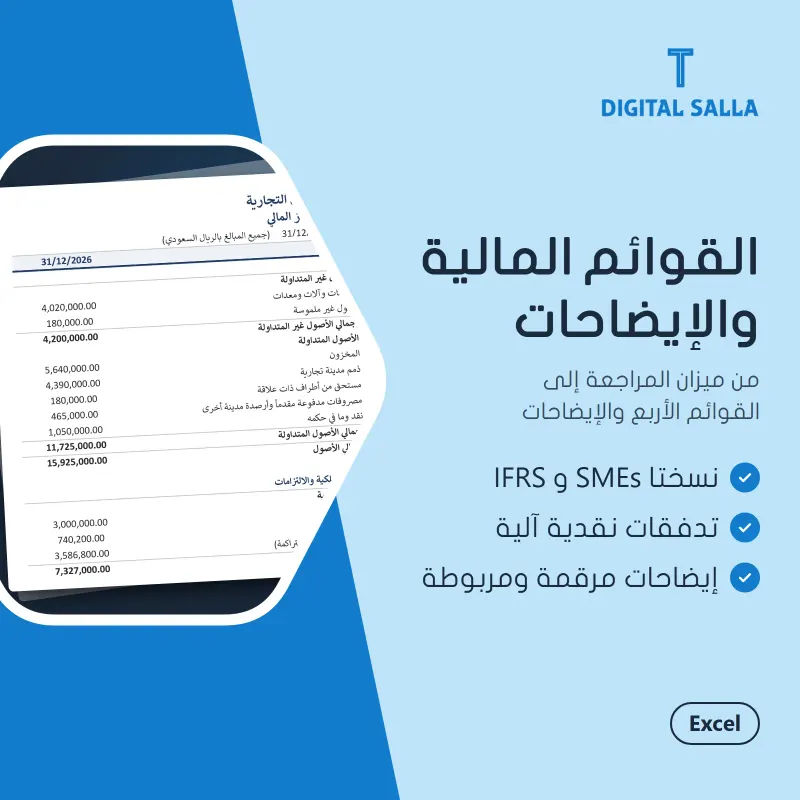
Enter the trial balance once to get the four financial statements, including an automatic cash flow statement, plus notes and ratios — in two editions: IFRS for SMEs, and full IFRS (IAS 1 presentation for 2026, IFRS 18 automatically from 2027).
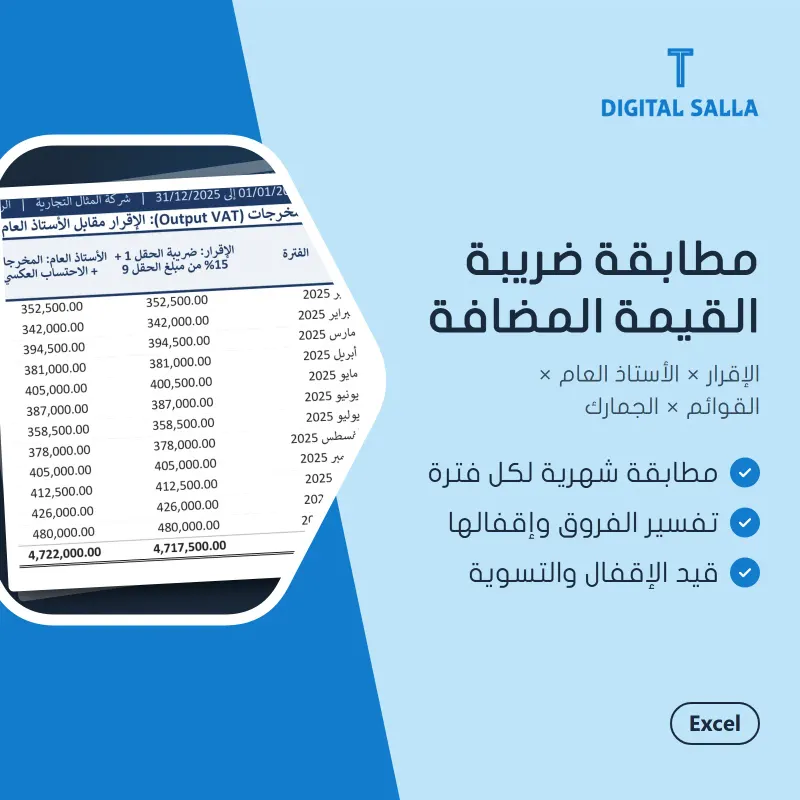
Reconcile VAT returns with the general ledger monthly, and with revenue in the financial statements, the zakat return and customs data annually — before the authority finds the differences.
Ready objection memo templates for the most common zakat and tax assessment items, with the supporting-documents list and the statutory deadlines schedule.
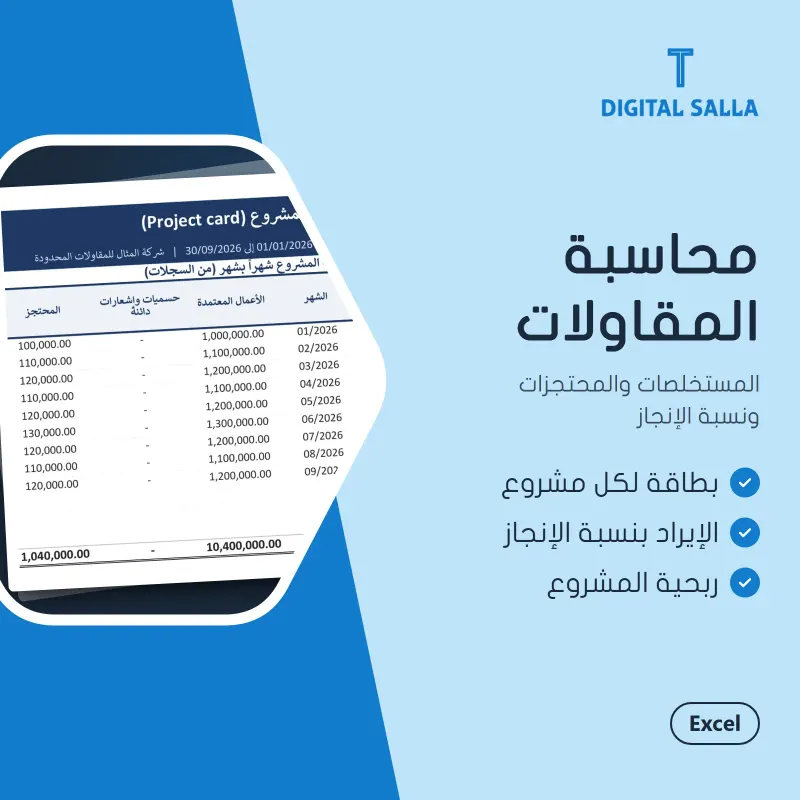
Track each project's progress billings, retentions and their VAT, compute revenue by percentage of completion and each project's profitability against its budget, with the entries and the note ready.
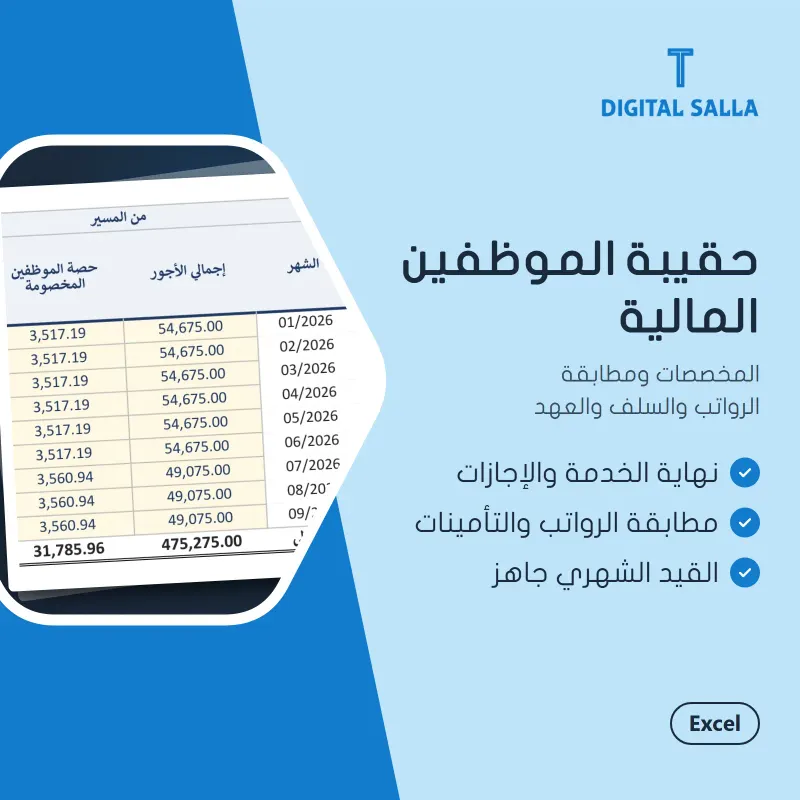
Compute end-of-service, leave and ticket provisions for all your employees monthly, reconcile payroll with the GOSI invoice and the general ledger, and track advances and custody, with the monthly entry ready.
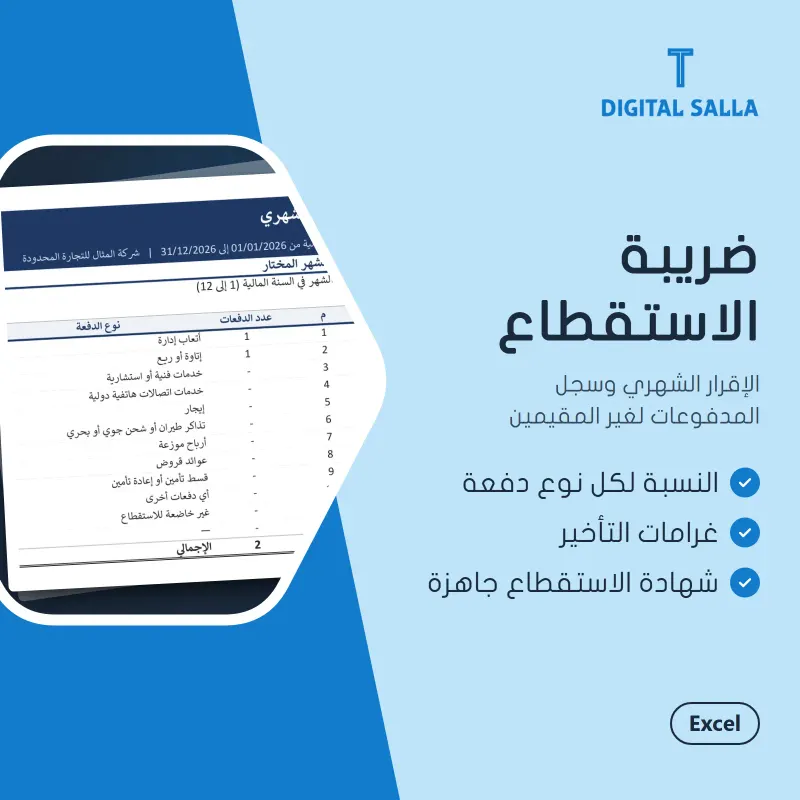
Record your payments to non-residents and classify the withholding rate for each, compute the monthly return and late penalties, with the entries and the annual reconciliation.
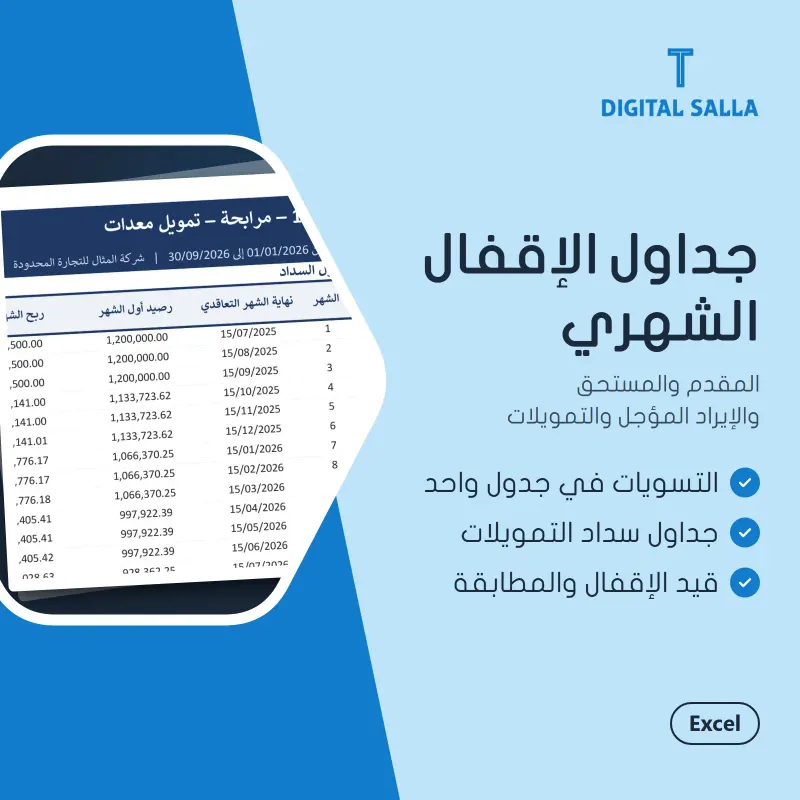
One schedule for every month-end adjustment — prepaid expenses, accruals, deferred revenue and bank financing — that generates the closing entries and reconciles the balances with the trial balance.
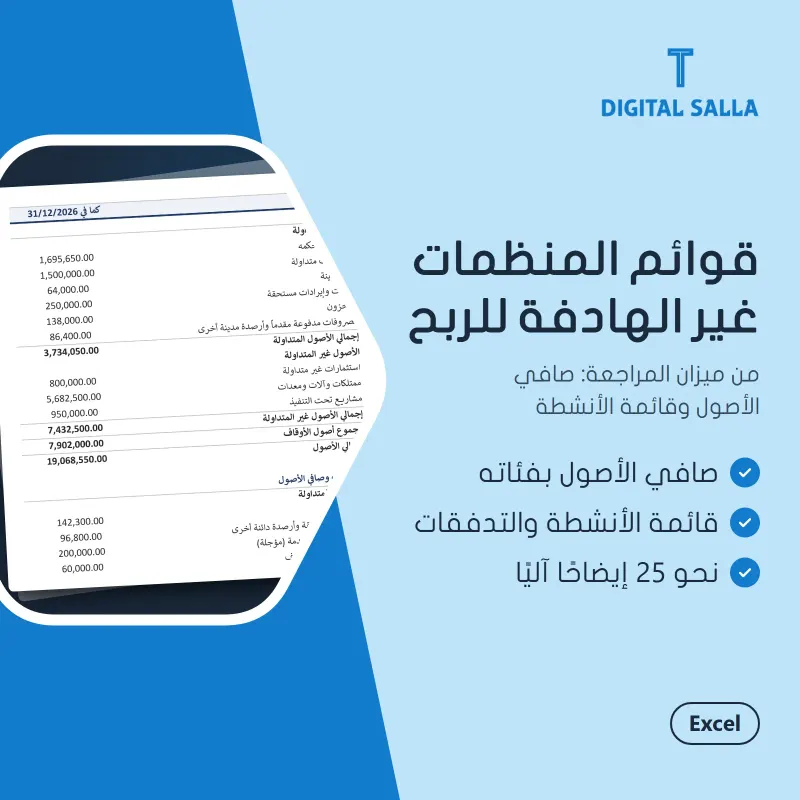
Enter the association's trial balance to get its financial statements and notes: restricted and unrestricted net assets, the statement of activities, and in-kind donations.
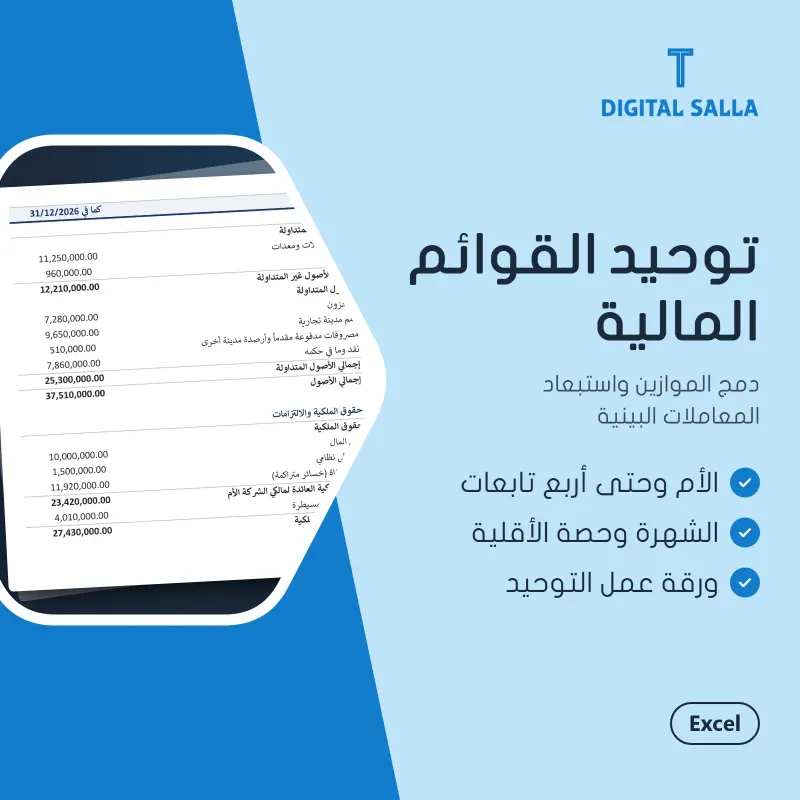
Merge the companies' trial balances, eliminate intercompany balances and transactions, and compute non-controlling interests and goodwill, to produce ready consolidated statements.
We prepare your expected credit loss model and the methodology memo, built to meet what external auditors usually ask for, at a lower cost than the large firms.
Compute the right-of-use asset and lease liability for all your contracts under IFRS 16, with monthly entries, contract modifications, the current portion, and the note ready.