Expected Credit Loss Assessment and Methodology Memo Service (IFRS 9)
We prepare your expected credit loss model and the methodology memo, built to meet what external auditors usually ask for, at a lower cost than the large firms.
Instant digital delivery · Secure international payment · Files updated with every regulatory change
A provision-matrix model for expected credit losses under IFRS 9: historical default rates, forward-looking adjustment, provision movement and the note.
Launch price until 18 December 2026 — then the base price returns automatically.
Applied to the base price; the lower of it and the launch price wins.
Save with the bundle
"Full IFRS Bundle" includes 4 products for SAR 1,199 instead of SAR 1,716 — save 30%.
View the bundleSave with the bundle
"Complete Bundle – All Paid Products (16 files)" includes 16 products for SAR 2,799 instead of SAR 5,374 — save 48%.
View the bundle| Category | Full IFRS |
|---|---|
| Type | Digital Product |
| Format | Excel |
| Version | 1.0 |
| Files |
|
A provision-matrix model for expected credit losses under IFRS 9: historical default rates, forward-looking adjustment, provision movement and the note.
The product and its files are in Arabic.

We prepare your expected credit loss model and the methodology memo, built to meet what external auditors usually ask for, at a lower cost than the large firms.

Compute the right-of-use asset and lease liability for all your contracts under IFRS 16, with monthly entries, contract modifications, the current portion, and the note ready.

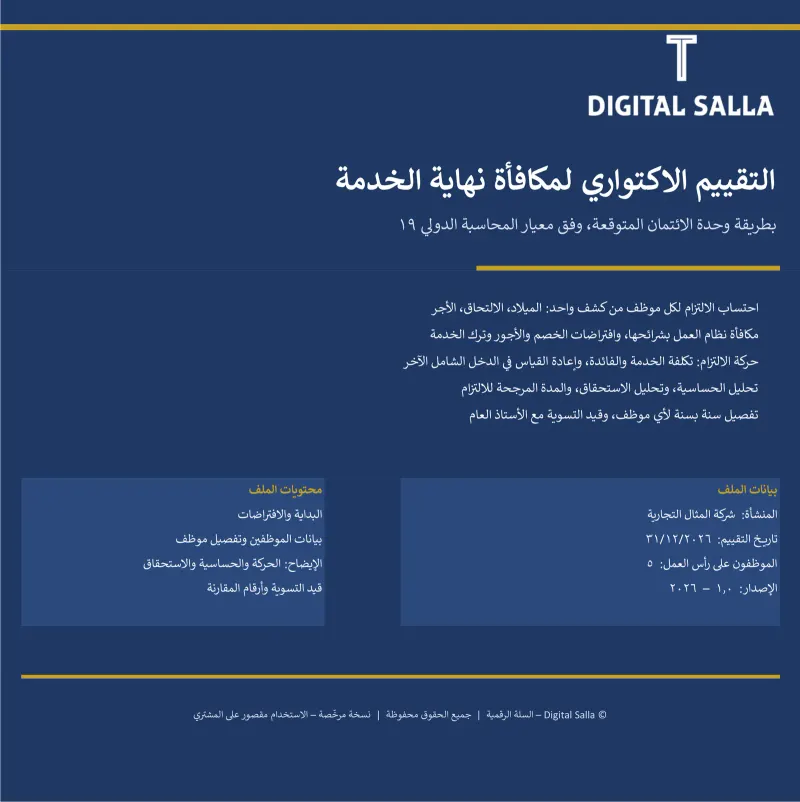
Compute the end-of-service benefit obligation by the projected unit credit method under IAS 19, with actuarial gains and losses, sensitivity analysis and the note.

Four related products for one price below the sum of their individual prices; every file is delivered on payment.